The First-Time Home Buyer Guide to Sioux Falls
Buying your first home in Sioux Falls is more achievable than most people think. There's no state income tax, a strong job market, and more help available than most first-time buyers realize. I'm Jennifer Krosch, a Broker Associate with eXp Realty, and I've helped first-time buyers get here with 10+ homes sold and a background in construction and electrical work, so I can tell you what a home will really cost to own before you fall in love with it. This guide walks you through the whole process, what it actually costs, and the help that exists.
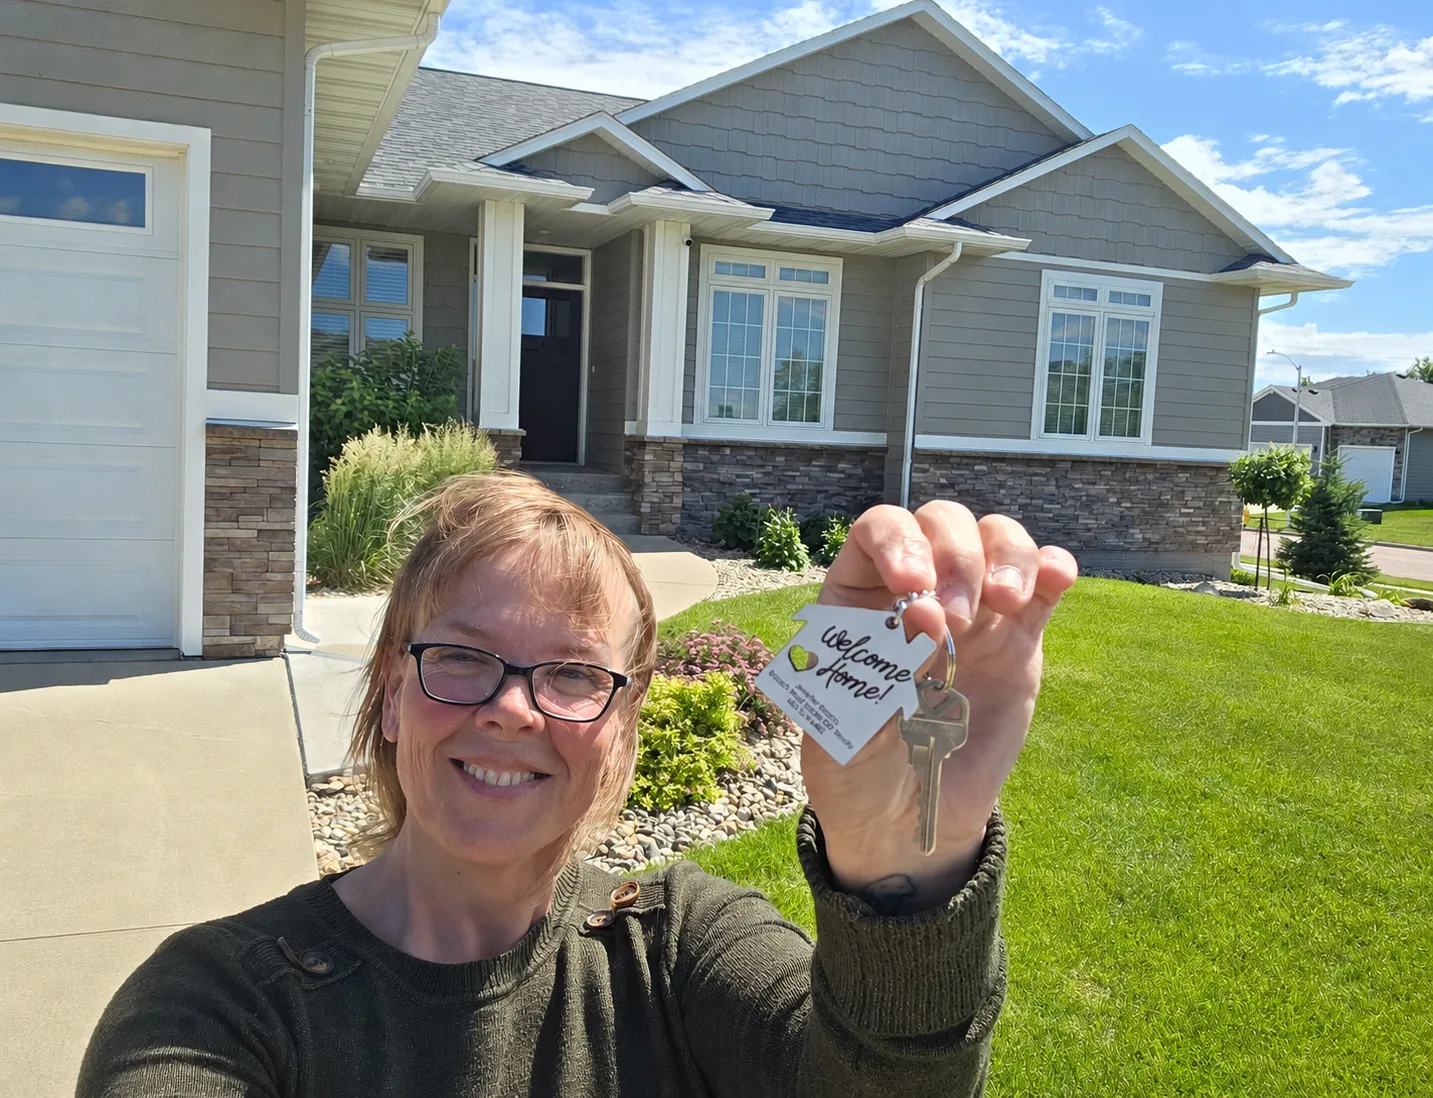
Getting the keys is the moment it becomes real. I help you get there with confidence.
Why Sioux Falls works for first-time buyers.
Every market has reasons to buy, but Sioux Falls stacks the deck in a first-time buyer's favor: affordable entry prices, no state income tax, steady job growth, and a four-season lifestyle. Here's what that looks like in practice:
Affordable entry prices
Home prices in Sioux Falls run slightly below the national median, and the cost of living here lands roughly 9% under the U.S. average. Your first-home budget simply goes further here than it does in most metros.
No state income tax
South Dakota has no state individual income tax, so more of every paycheck is yours to put toward your mortgage, your savings, and the life you're building.
A job market that keeps growing
Healthcare is the big driver, with Sanford Health and Avera Health among the region's largest employers, and finance, manufacturing, logistics, and small business round out a steady, diverse economy. That growth keeps the resale market healthy.
A real four-season lifestyle
Sioux Falls is a genuine four-season city: trails and parks along the Big Sioux, Falls Park downtown, festivals through the summer, and enough winter to make a fireplace feel essential. There's something for every season of your life.
Starter price points across the metro
From established east-side neighborhoods to the growth areas in the south and the nearby communities of Brandon, Harrisburg, and Tea, there are genuinely affordable entry points for a first home.
If you're relocating, the relocation guide covers cost of living, schools, commuting, weather, and what it's like to land here, all in one place. And for deep dives on the metro's favorite communities, start with the Brandon, Harrisburg, and Tea guides.
The 7-step process, in order.
Buying a home is a sequence, not a mystery. Here's exactly how it goes, from your first budget conversation to the day you get the keys.
Know your finances and credit score
Before you look at a single listing, get a real picture of your numbers: your credit score, your debts, and a monthly budget you can live with. Your credit score shapes the rates you qualify for, so check it early and fix what you can before you shop.
Get pre-approved before you look
Sellers and agents take pre-approved buyers seriously, and in Sioux Falls's popular price ranges, well-priced homes often draw multiple offers. A pre-approval letter from a local lender tells you exactly what you can afford and lets you move fast when the right home hits the market.
Build your team: agent, lender, home inspector
You want people who know this market. I can connect you with local lenders who work with first-time buyers and inspectors I trust, so the three of you start the process aligned from day one.
Define the must-haves and your neighborhood shortlist
Bedrooms, garage, commute, schools, yard, walkability. We rank what matters, then shortlist neighborhoods that fit both your budget and your lifestyle, so your search stays focused instead of endless. One rule that saves a lot of first-time buyers from buyer's remorse: you can update a kitchen, but you can't change the neighborhood.
Tour homes
This is where a builder's eye pays off. As we walk properties, I'll point out what's a real concern and what's normal wear, so you compare homes by true condition rather than by staging and paint.
Make an offer with your agent's guidance
When you find the one, I'll help you craft a competitive offer backed by current market data, explain every line of the purchase agreement in plain language, and negotiate on your behalf.
Inspection, appraisal, closing
Your inspection contingency protects you, the appraisal protects the lender, and then we walk through closing together. A few weeks after your offer is accepted, you get the keys.
Money reality check: what it actually costs.
The purchase price is not the whole story. Between your offer and your first year as a homeowner, these are the line items that show up. None of them should scare you, but all of them should be planned for.
Earnest money
A good-faith deposit held in escrow when your offer is accepted. It shows the seller you're serious and is credited toward your down payment at closing, so it's not a lost cost.
Home inspection
Typically a few hundred dollars in Sioux Falls, and the single best money you'll spend. This is where my construction background matters: I walk the property with you and help you understand what the report really means.
Appraisal
Usually a few hundred dollars, ordered by your lender to confirm the home is worth what you're paying. It protects you from overpaying and the lender from over-lending, and it's part of your closing costs.
Closing costs
The fees to process and finalize your loan and transfer ownership: lender fees, title work, and related charges. Buyers in this market often pay roughly 2% to 5% of the purchase price, and several assistance programs can help cover them.
Homeowner's insurance
Required by your lender. It protects the home and your belongings, and in South Dakota it usually covers the hail, wind, and winter claims that are part of life here. It's paid annually or with your monthly mortgage.
Property taxes
Your lender typically collects property taxes with your monthly mortgage payment. South Dakota has no state income tax and funds local services through property and sales taxes, so your lender's tax estimate matters when you compare monthly payments.
Utilities
Heating and cooling a home through a South Dakota winter and summer is a real line item. A home's insulation, windows, and the age of its furnace matter a lot here, another place my construction background helps you budget honestly.
Maintenance cushion
A common rule of thumb is to set aside 1% to 2% of your home's value each year for maintenance and repairs. Older homes and homes with aging systems can need more; newer homes often need less.
The old rule that you need 20% down keeps a lot of people out of the market longer than necessary. FHA loans allow as little as 3.5% down, and many conventional loans allow 3% for qualified buyers. Put down 20% and you avoid private mortgage insurance (PMI), but many first-time buyers put down less and plan to refinance or drop PMI later. Don't let the "20% rule" talk you out of a conversation about your options.
The inspection is the place my construction background pays you directly. It's typically a few hundred dollars, and I walk it with you so you understand what the report means. Read the full home inspection guide for what's covered and how to read it without panicking.
Read the Home Inspection GuideDown payment and closing cost help in South Dakota.
This is the part most first-time buyers don't realize exists. South Dakota has a genuinely strong lineup of programs that can put thousands of dollars toward your down payment and closing costs. Here are the main players:
SD Housing (SDHDA) First-Time Homebuyer Program
The South Dakota Housing Development Authority, now SD Housing, offers first-time buyers special mortgages with competitive rates and down payment assistance of 3% or 5% of the loan amount through its Fixed Rate Plus options. The assistance is a 0% interest second mortgage, due when you sell or refinance. Income and purchase price limits apply by county, and you must work with a participating lender. You generally qualify as a first-time buyer if you haven't owned a home in the past three years.
City of Sioux Falls Homebuyer Assistance Program
Forgivable loans of up to roughly $8,000 for down payment and closing costs for eligible low-to-moderate income buyers. Typical requirements include being a first-time buyer, household income at or below 80% of the Sioux Falls area median income, and completing homebuyer education. The City updates income limits and rules regularly, so current details matter.
GROW South Dakota
A statewide nonprofit lender offering down payment and closing cost assistance of up to roughly $10,500 for income-qualified buyers, with most awards landing in the $5,000 to $7,500 range. It's structured as a 0% interest, deferred-payment loan repaid when you sell, refinance, or stop living in the home. Eligibility and amounts vary by region and by funding availability.
Mortgage Credit Certificate (MCC)
A SD Housing tax credit that lets eligible first-time buyers claim a percentage of their mortgage interest as a dollar-for-dollar reduction in federal income tax, worth as much as roughly $2,000 a year for the life of the loan. You claim it annually on IRS Form 8396, and it's arranged through a participating lender before you buy.
These programs change: income limits, purchase price caps, and funding availability shift over time, and every program has specific eligibility rules. The figures above are a starting point, not a guarantee. A local lender who participates in these programs is the one who confirms what you actually qualify for, and that's exactly where my lending partners come in. I'll connect you with lenders who know these programs cold, so you find out what's real for your situation instead of guessing.
Best neighborhoods for first-time buyers in Sioux Falls.
There's no single "right" first home, but there are areas where first-time buyers consistently do well. Here's a practical take on commute, schools, price point, and vibe for the main starter-friendly parts of the metro.
Southern Sioux Falls growth areas
Newer developments, family-friendly layouts, and a steady supply of homes across starter and move-up price points. Commutes into central Sioux Falls are quick, and the newer neighborhoods are built with parks and schools in place.
Explore the guideEstablished east-side neighborhoods
Mature trees, settled streets, and a real mix of housing from starter homes to larger family properties. Often more home for the money, with easy access to shopping, dining, and I-29.
Explore the guideCentral neighborhoods near downtown
Historic character, walkable streets, and condos and starter homes near the restaurants and events around downtown and Falls Park. Ideal for buyers who want less lawn and more neighborhood.
Explore the guideBrandon, Harrisburg, and Tea
The metro's most popular suburb choices for first-time buyers: Brandon and Harrisburg for top school districts, Tea for approachable entry prices and new builds. Each is a short drive into Sioux Falls.
Explore the guide
Jennifer Krosch · eXp Realty · License #21816
First-time buyers deserve an agent who knows what a home really costs.
With more than 20 years in construction and electrical work, plus time with the City of Sioux Falls, I read a house the way it was built: what's solid, what's aging, and what will cost you money in the first five years of ownership. That's exactly the education a first-time buyer needs, because the cheapest house on the block is rarely the cheapest house to own.
- Honest walkthroughs: I point out the positives and the red flags on every tour, in plain language.
- Real cost expectations: roofs, panels, furnaces, and grading, and what they'll cost you down the road.
- Local program knowledge: I connect you with lenders who know the SD Housing, City, and GROW programs cold.
- First-time buyer patience: this is your first time. I'll explain every step, every form, and every deadline until it makes sense.
Questions I hear from first-time buyers in Sioux Falls.
How much do I need for a down payment in Sioux Falls?
It depends on the loan you qualify for. FHA loans allow as little as 3.5% down, and many conventional loans allow 3% for qualified buyers. South Dakota's SD Housing program can provide down payment assistance of 3% or 5% of the loan, and city, state, and nonprofit programs can cover part of the down payment and closing costs for eligible buyers. A local lender who knows these programs can give you the honest number for your situation.
Can I buy with less than 20% down?
Yes, most first-time buyers in Sioux Falls do. FHA loans start at 3.5% down and conventional loans can go as low as 3% in many cases. When you put down less than 20%, you typically pay private mortgage insurance (PMI), but that can be a worthwhile trade-off for getting into a home years sooner than waiting to save 20%.
What are closing costs?
Closing costs are the fees to process and finalize your loan and transfer ownership, including lender fees, title work, the appraisal, and related charges. Buyers in this market typically pay roughly 2% to 5% of the purchase price. Several of the assistance programs in this guide can help cover those costs for eligible buyers.
How do I get pre-approved?
You work with a lender who reviews your income, credit, and debts and issues a pre-approval letter stating the amount you can borrow. You'll provide your credit score, pay stubs, tax returns, and bank statements. I can connect you with local lenders who work with first-time buyers every week.
What credit score do I need?
Most conventional and FHA lenders look for a score around 620 or higher, and FHA guidelines can be more flexible in some cases. Higher scores usually mean better rates, so check your score early and give yourself time to improve it before you start shopping.
Do I need a real estate agent to buy a home?
You don't legally have to use one, but I wouldn't recommend going it alone on your first purchase. An agent who knows Sioux Falls will help you price your offer, negotiate, read the inspection, and keep every deadline straight. In most transactions the buyer's agent is paid from the seller's side of the deal, so you get the help without an added fee.
What is the Sioux Falls first-time home buyer program?
There isn't one single program. The main players are SD Housing (South Dakota's housing authority), which offers first-time buyer mortgages with 3% or 5% down payment assistance; the City of Sioux Falls Homebuyer Assistance Program, with forgivable loans of up to about $8,000; and GROW South Dakota, with up to roughly $10,500 in assistance for income-qualified buyers. A participating local lender confirms which ones you qualify for.
Do I really need a home inspection?
Yes. It's the one time a professional examines the whole house before you own it, and it costs a few hundred dollars. With my construction background, I walk it with you and help you separate genuine concerns from normal wear. You can read my full home inspection guide for what a report covers and how to read it without panicking.
Should I get an inspection on a new construction home?
Absolutely. Even new construction can have defects. My construction background is especially valuable here: I know what builders sometimes miss, and what to look for in new builds versus resale homes.
Ready to find your home in Sioux Falls?
Let's walk through it together. Search the latest homes across the Sioux Falls metro, book a no-pressure consultation, or just give me a call. Whether you're buying, selling, or relocating from out of state, I'll help you feel confident at every step.
Jennifer Krosch, Realtor · eXp Realty · License #21816 · Realtors of the Sioux Empire