How to Evaluate the Cash Flow of a Sioux Falls Twin Home or Townhome
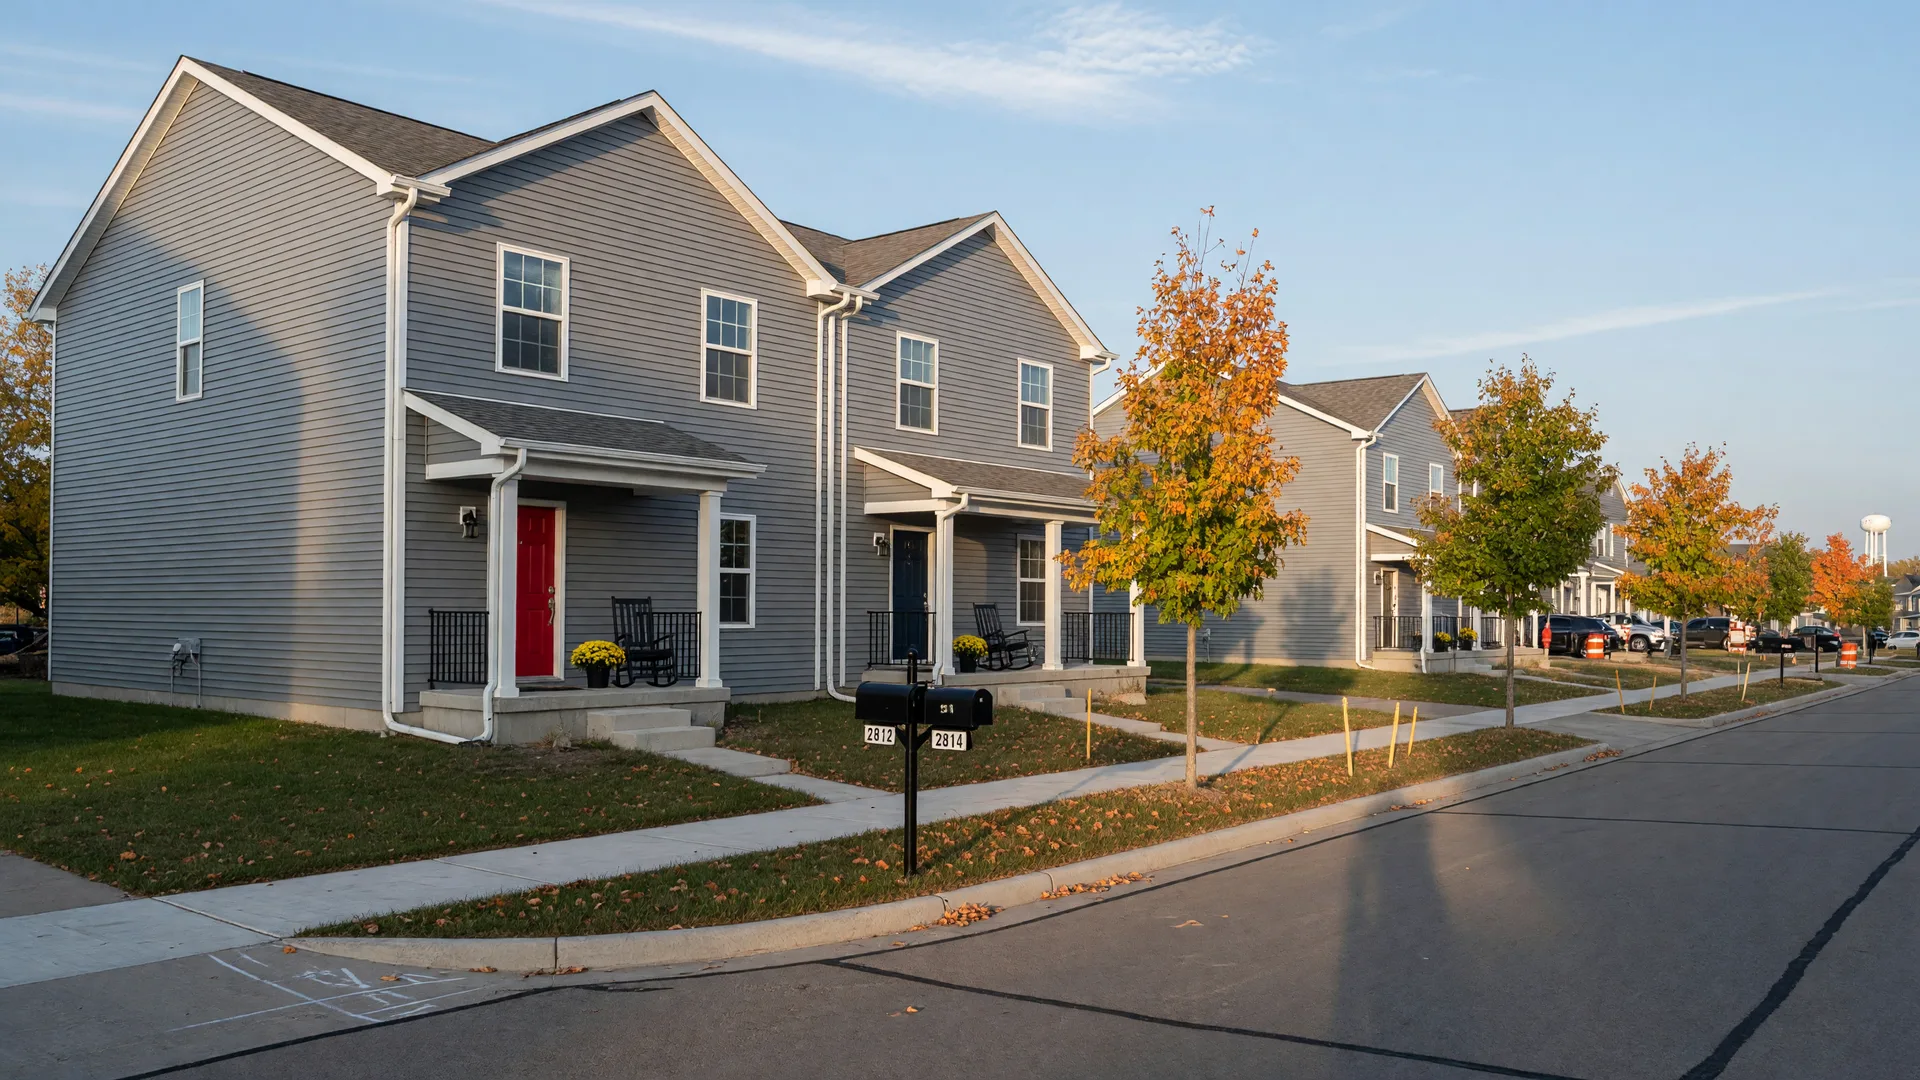
Evaluating the cash flow of a Sioux Falls twin home or townhome comes down to one formula you can run by hand: rental income, minus vacancy, minus operating expenses, gives you net operating income, and then subtracting the mortgage payment gives you cash flow. This guide walks each step in order, with clearly labeled illustrative examples, so you can judge whether a specific property makes sense before you make an offer. Every number here is an estimate to verify with current comparables and real quotes, never a guarantee.
The Cash-Flow Equation, Step by Step
The whole analysis fits into a single sequence, and it helps to write it out in the same order every time. For any property you underwrite, work down this list:
- Estimate the monthly rent for the specific unit and the neighborhood, then annualize it.
- Apply a vacancy allowance to that gross rent to get effective rental income.
- List every operating expense: property taxes, insurance, HOA dues, repairs and maintenance, property management, and an allowance for other costs.
- Subtract operating expenses from effective rental income to get net operating income (NOI).
- Divide NOI by the purchase price to see the cap rate.
- Estimate the mortgage payment (debt service) using your actual financing assumptions.
- Subtract debt service from NOI to get cash flow.
Each step is a projection built on assumptions, so the value of the exercise is not the final number, it is knowing which assumption each line depends on. The same frame works for a new-construction townhome, an existing twin home, or any other attached rental in the metro, and it is the frame I use when an investor asks whether a property earns its keep.
Step 1: Rent Projections Are Projections, Not Guarantees
The rent line anchors the entire analysis, and it is also the easiest number to get wrong. An automated estimator, a seller's marketing sheet, or a hopeful guess can all point one direction, but what actually matters is what comparable units in that exact neighborhood have recently leased for, not what they are listed at. Asking prices sit above closed deals, so use leased rents when you can find them and adjust for size, finishes, garage space, and location within the metro.
Check whether your comparables are the same product type, a twin home versus a townhome versus a single-family, because they rent differently. Look at the lease terms, since a longer minimum term can change the effective monthly rent. Then fold in a realistic assumption about occupancy and vacancy: if the neighborhood has several units sitting empty or units taking months to lease, assume a higher vacancy allowance and a more conservative rent. Rent and occupancy assumptions drive everything after them, so stress-test the deal at a lower rent and a higher vacancy before you trust the result. A deal that only works at the most optimistic rent is not a deal you can underwrite safely.
Step 2: Operating Expenses: The Checklist Investors Should Itemize
Operating expenses are everything the property costs you between rent checks, and they are too often understated with a single generic percentage. Itemize every line for the specific address instead, then total them. A practical checklist for a Sioux Falls twin home or townhome:
- Property taxes. Verify the expected annual amount with the county or the seller's most recent bill, and remember a new build is often assessed at its full new value.
- Insurance. A landlord or rental-property policy with dwelling coverage, liability, and possibly loss of rent, quoted at today's replacement cost. Get an actual quote from an insurer, not a guess.
- HOA dues. Attached homes in the Sioux Falls area frequently carry an HOA or property owners association, so pull the current dues, the budget, and the reserves, and check whether the association covers the roof, siding, common walls, and snow removal. Dues can increase.
- Repairs and maintenance. A running reserve for upkeep, turnover cleaning, small fixes, and the eventual big-ticket replacements. Newer properties are lighter early on, but it is never zero.
- Property management. If you plan to hire a manager, the fee is typically a percentage of collected rent. If you self-manage, budget for the value of your own time.
- Vacancy and turnover. The months the unit sits empty plus the cost of preparing it for the next tenant.
There is a reason to itemize rather than guess: one missing line item quietly inflates your projected cash flow, and a property that looked fine on a two-line back-of-napkin calc can be a different story once the association dues and the vacancy allowance land on the sheet. When you have the specific numbers, the investment calculator on the Investor Hub does this exact arithmetic for you, and the Investor Resources hub collects the rest of the education on evaluating Sioux Falls rental property.
Step 3: Net Operating Income (NOI)
Net operating income is effective rental income minus operating expenses, calculated before any mortgage payment. It answers one question: what does this property earn from its rental operations, independent of how you finance it? Because NOI ignores financing, it is the cleanest number for comparing one property to another, and it is the base for the cap rate.
To get effective rental income, take annual gross potential rent and subtract your vacancy allowance. Then subtract the operating expenses you itemized in the step above. The result is NOI. If the NOI does not cover a healthy share of your financing cost, no amount of leverage will turn the property into a comfortable rental, so this line is worth looking at carefully before you ever call a lender.
Step 4: Cap Rates: A Rough Comparison Tool
The cap rate is NOI divided by purchase price, expressed as a percentage. It is one common metric investors use to compare properties and markets quickly, and it answers: at this price, what does the property yield before financing? A price drop or rise changes the cap rate even when the income is identical, which is precisely why it is a rough tool rather than a verdict.
A higher cap rate usually signals either a stronger yield or a riskier, older, or less liquid property, and a lower cap rate usually signals either a lower yield or a newer, higher-demand property investors are willing to pay more for. Because of that, a cap rate only means something compared with other similar properties on the same basis, and it must always sit alongside the full analysis, the verified rent, the itemized expenses, and the actual financing. No single metric, cap rate included, tells you whether a property is a good investment.
Step 5: Mortgage Payments (Debt Service)
Debt service is the annual total of your mortgage payments, principal and interest, and it depends on the purchase price, the loan amount, the interest rate, the loan term, and your individual financing picture, including how much you put down and your credit situation. Two investors can carry the same building at very different costs, one with a 20% down payment and one with a larger down payment, so the honest way to estimate debt service is to get real quotes from a lender, not to assume a generic rate.
A few practical notes: rates, points, and program terms change constantly, and your specific situation decides which program you qualify for. Run the payment on the loan amount you actually expect, not on the full purchase price, and remember the monthly payment is only principal and interest at this stage. Property taxes and insurance are already sitting in your operating-expense checklist above, and financing them into a mortgage does not remove them, it just moves the timing.
Step 6: Cash Flow = NOI Minus Debt Service
Cash flow is NOI minus debt service. It is the number most investors mean by \"does it cash flow\", the money left over after the property covers its operating costs and its mortgage. Financing assumptions drive most of the difference in cash flow between two similar properties, because the operating side, the rent, and the expenses tend to look alike for comparable units, while the loan amount, rate, and down payment can swing the monthly result by hundreds of dollars.
Cash flow is also before principal paydown, appreciation, and tax treatment. A property can show a negative cash flow month to month and still build equity and gain value, just as a property can show positive cash flow and still underperform when you carry the maintenance yourself. The point of the exercise is to know your cash-flow number, label it honestly, and decide whether that trade-off fits your goals, rather than to chase a single positive line.
Illustrative Scenario A: A $449,000 Twin Home
This first example walks the full formula on a hypothetical twin home at a $449,000 purchase price. Every figure below is an illustrative estimate only, not an offer and not a guarantee of results. Your actual numbers will differ.
Illustrative Scenario A: $449,000 twin home
Work down the lines and the logic is easy to follow. The rent is strong on its face, but once the vacancy allowance, the itemized expenses, and the illustrative mortgage payment are on the sheet, the property lands below break-even on cash flow at these assumed inputs. That is a common pattern at higher price points right now: the monthly cost that scales with price, mostly the financing, outruns what the neighborhood's rents will actually support.
Illustrative Scenario B: A $349,000 Townhome Shows How the Math Scales
The same formula on a lower price point shows why entry price matters so much to cash flow. This second example is a hypothetical townhome at a $349,000 purchase price, again with every figure an illustrative estimate only, not an offer and not a guarantee.
Illustrative Scenario B: $349,000 townhome
The two scenarios share the same method, yet they land differently, which is the point. The cap rates are close, around 3% and 3.5%, because both properties earn a similar yield on price before financing. The real gap shows up in the bottom line: the lower entry price means a smaller loan, and therefore lower debt service, and the monthly shortfall narrows by roughly $400 a month even before you consider a larger down payment or a lower rate. Financing assumptions drive most of the difference in cash flow.
In both scenarios, changing the assumptions changes the result. A larger down payment, a better rate, a verified higher rent, or a lower vacancy allowance can each move the bottom line, and none of them is guaranteed. The honest way to test your own numbers is to plug your real price, rent, expenses, and financing into the interactive investment calculator on the Investor Hub and see every line for yourself.
Putting It Together for Sioux Falls Investors
Cash-flow analysis for Sioux Falls investment properties is not about finding one magic number; it is about building a habit of writing every assumption down and testing it. Start with verified rents for the specific neighborhood, itemize the operating expenses instead of guessing, keep the cap rate as one comparison among many, and get real financing quotes rather than assuming a rate. Then decide whether the resulting cash flow, together with principal paydown, appreciation, and tax treatment, fits your goal.
If you are new to the process, the Investor Resources hub is the place to begin, and it links the cornerstone articles that build on this one: whether a brand-new townhome works as a rental, new construction versus existing rental properties, and what a year-end 2026 purchase timeline really involves. For current information on the twin homes and townhomes I track, request the investor property report and I will walk you through the numbers on a specific property. And for anyone comparing Sioux Falls townhomes for sale or Sioux Falls twin homes as rental property, the same verified-rent and itemized-expense discipline is exactly what separates a realistic underwrite from a hopeful one.
About the author
Jennifer Krosch, Broker Associate · eXp Realty
Jennifer is a Realtor and Broker Associate with eXp Realty in Sioux Falls, licensed in South Dakota (license 21816). Her background across construction, electrical work, and workplace safety, including prior work with the City of Sioux Falls, gives her a practical eye for the condition and long-term value of a home, which makes her a steady guide for Sioux Falls real estate investors evaluating rental property. More about Jennifer · Client reviews
Frequently Asked Questions
What is cash flow on a rental property?
Cash flow is what is left over after you subtract debt service, the mortgage payment, from a property's net operating income (NOI). In practice: annual rental income minus a vacancy allowance minus operating expenses gives you NOI, and then subtracting the annual mortgage payment gives you cash flow. A positive number means the property covers its own month-to-month costs before you consider principal paydown, appreciation, or tax treatment; a negative number means you are covering the shortfall out of pocket. Cash flow is a projection based on your assumptions, not a guarantee.
What is a good cap rate?
There is no single universal answer, because a cap rate is a rough comparison metric, not a verdict. It is NOI divided by purchase price, expressed as a percentage. A higher cap rate often comes with an older property, higher maintenance, or a less liquid market, while a lower cap rate often comes with a newer or higher-demand property, which is why the number only means something when you compare it with similar properties on the same basis. What counts as "good" depends on the property type, the neighborhood, current financing costs, and your own goals, and the cap rate should always be used alongside the full cash-flow analysis rather than on its own.
How is NOI calculated?
Net operating income (NOI) is effective rental income minus operating expenses, calculated before any mortgage payment. You start with annual gross potential rent, subtract a vacancy allowance to get effective rental income, then subtract operating expenses such as property taxes, insurance, HOA dues, repairs and maintenance, property management, and an allowance for vacancy and turnover. What remains is what the property earns from rental operations before financing, and it is the number you divide by purchase price to get the cap rate.
What is a vacancy allowance?
A vacancy allowance is a realistic estimate of the time and money a rental sits empty between tenants, plus the turnover costs of getting the unit ready for the next tenant. Investors usually express it as a percentage of annual gross rent; the illustrative examples on this page use 5%. Every rental experiences vacancy eventually, so underwriting with a vacancy allowance rather than assuming 100% occupancy gives you a more honest picture of cash flow and keeps optimistic assumptions from hiding real costs.
Are the rent and cash-flow numbers on this page guarantees?
No. Every figure on this page is an illustrative estimate, not an offer and not a promise of results. Rent estimates are projections that must be verified against current comparable rents in that specific neighborhood, and expenses, vacancy, interest rates, and market conditions all change over time. No investor can guarantee rent, occupancy, cash flow, appreciation, or returns. Before making an investment decision, review a specific property's numbers with a licensed real estate professional and consult your CPA, tax advisor, and attorney.
Estimates disclaimer
All investment figures on this page are illustrative estimates only and are not offers or guarantees. Rental income, occupancy, cash flow, appreciation, and returns are projections, not promises, and actual results will vary based on the real purchase price, financing, rents, vacancy, expenses, and market conditions. Nothing here is a substitute for a professional property-specific analysis, and Jennifer does not provide licensed home inspection, tax, or legal advice: for those, work with a licensed inspector, CPA, tax advisor, and attorney. Investors should consult qualified tax and legal professionals before making any investment decision.
Working through a specific Sioux Falls twin home or townhome as a rental? I'll help you verify the rents, itemize the expenses, and stress-test the cash flow on a property you are considering. Call or text 605-214-6482, or book a consultation online. No pressure, no guesswork.
Related guides
Investor Resources: the investor education hub from Jennifer Krosch, with cornerstone guides and tools for evaluating Sioux Falls rental property.
Sioux Falls Investment Properties: the Investor Hub, including the interactive investment calculator for running your own cash-flow scenarios.
Request the investor property report: get current details on new-construction twin homes and townhomes available to investors, by request.
Is a Brand-New Townhome a Good Rental Investment in Sioux Falls, SD?: the advantages, price premium, and HOA rental rules of new construction.
New Construction vs. Existing Rental Properties: the side-by-side comparisons investors should make before buying.
Buying a Rental Property Before December 31, 2026: what the year-end acquisition timeline really involves.
Contact Jennifer Krosch: start the conversation about your next home or investment.